Private sector financing
Private capital is an important but volatile component of Africa’s infrastructure financing. Commitments fell sharply after 2020 before recovering in 2023, with investment concentrated in a limited number of sectors and regions.
A recovery after a sharp decline
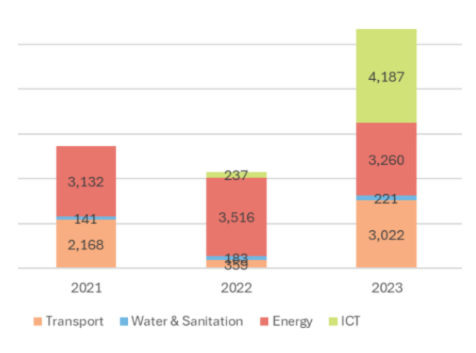
Private-sector infrastructure commitments fell from approximately US$19 billion in 2020 to US$5.4 billion in 2021, declined further in 2022 and recovered to approximately US$10.6 billion in 2023. The private share of total commitments was around 6% in 2021, 4% in 2022 and 10% in 2023.
Sectoral and geographic concentration
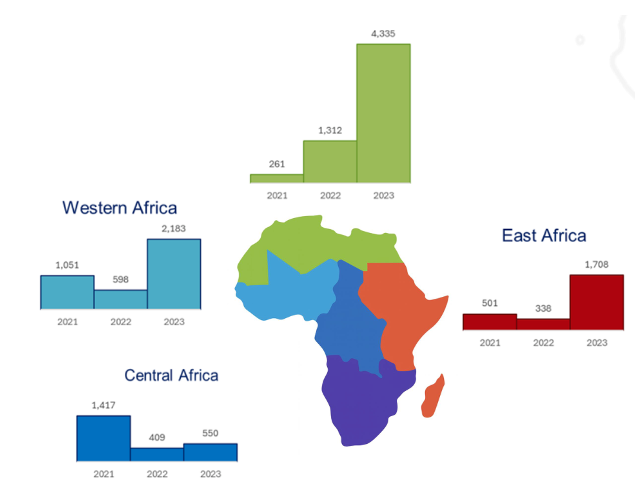
Across 2021–2023, energy attracted 48% of recorded private infrastructure commitments and transport 27%. Financing was concentrated particularly in North and Southern Africa. Large transactions can materially influence annual and regional totals, so the figures should not be interpreted as evenly distributed investor interest.
Examples of private-financed projects
The report identifies major transactions including the Port of Banana in the Democratic Republic of Congo, the Kenhardt solar photovoltaic project in South Africa and Senegal’s Port of Ndayane. These examples illustrate the importance of large transport and energy investments in the recorded totals.
Conditions for mobilising more investment
The 2023 rebound demonstrates that private financing can recover, but its contribution remains modest relative to Africa’s infrastructure requirements. Bankable project preparation, credible revenue arrangements and appropriate allocation of project risks are relevant to attracting additional private capital. These are policy implications, not outcomes directly measured by the commitment data.